
Massive Fines Hit Rogue Builders Over Fake Insurance
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
On July 19th, 2024, in a significant crackdown on fraudulent building practices, Aycon Constructions along with its director, Seyit Ayranci, received a record-setting fine of $250,000 from the Victorian Building Authority (VBA).
The enforcement action came after the construction firm was implicated in the use of falsified insurance certificates to secure building permits.
Investigations by the VBA revealed that Aycon Constructions had backed over 150 building permit applications with counterfeit domestic building insurance (DBI) records, performing building work without securing legitimate insurance policies. Builders in Victoria are legally obligated to obtain DBI for projects exceeding $16,000 to safeguard consumers and contractors alike.
The authority suspended Aycon’s operations in April after executing search warrants on multiple Melbourne sites, uncovering that the firm had been functioning without the essential DBI policies. The Victorian Managed Insurance Authority (VMIA) substantiated these findings, indicating that Aycon had not only bypassed obtaining insurance for several projects but had also replicated VMIA’s logo for these false certificates.
In response to these egregious violations, Mr. Ayranci’s registration as a builder has been revoked, and he has been disqualified from the industry for three years — the maximum duration allowed under current legislation. The VBA classified Ayranci as “unfit and improper,†also stating that his actions epitomize unprofessional conduct.
Anna Cronin, Commissioner and CEO of the VBA, emphasized the regulator's unwavering stance against disreputable builders. "This unprecedented penalty exemplifies our commitment to using every tool in our regulatory arsenal to protect consumers from unethical practices and ensure compliance in the building industry," remarked Ms. Cronin. "We urge consumers always to verify their builder’s registration and confirm the presence of a valid DBI policy, which is a legal necessity."
The VBA continues to engage with affected clients of Aycon, having noted a "relatively small" yet concerning number of complaints filed in May. The agency seeks to support these customers as they navigate the repercussions of Aycon’s malpractice.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
A recent Australian Financial Complaints Authority determination involving a flooded farmhouse has put claims handling back under the microscope for rural policyholders, after the insurer was ordered to pay almost $432,000 across building repairs, additional temporary accommodation, professional costs and compensation for non-financial loss. The decision, dated 27 August 2026 and reported by Insurance News on 15 October 2026, is a useful reminder that the practical aftermath of a farm flood can extend well beyond the first clean-up. - read more
Recent industry attention on insurance claims linked to ex-Tropical Cyclone Alfred is a timely reminder that severe weather losses rarely stop at damaged buildings. For farms across storm and flood-exposed regions, the real cost of an event can include cut access roads, damaged fencing, spoiled fodder, machinery downtime, livestock movement issues and weeks of operational disruption. - read more
Australia’s latest seasonal bushfire outlook is a practical reminder that fire risk is not confined to the height of summer. For many farms, the exposure begins well before a catastrophic fire day is declared, as grass growth, drying winds, stored fodder, machinery movement and access limitations combine to create a more complex risk profile than a standard rural home policy can address. - read more
Fresh industry concern about repair delays after severe weather is highly relevant for Australian farms, where a damaged shed, washed-out access track or unavailable part can quickly interrupt day-to-day operations. While the wider insurance discussion often focuses on homes and commercial buildings, the same pressure points can be even more complex on rural properties because assets are spread out, specialist equipment is involved and local contractor availability may be limited. - read more
Renewed industry pressure to reduce insurance taxes has put affordability back in the spotlight for rural and regional Australia. The latest debate centres on the extra costs added to insurance through state-based duties, levies and other charges, which can make already expensive cover harder to maintain for households and businesses exposed to flood, bushfire, storm and cyclone risk. - read more
Recent complaints data from the Australian Financial Complaints Authority has again highlighted a pressure point that matters to rural Australia: insurance claims can become difficult when expectations, policy wording and evidence do not line up. While the figures cover the wider insurance market rather than farms alone, the themes are highly relevant for agricultural businesses dealing with storm damage, fire losses, machinery failures, fencing repairs or interrupted operations. - read more
Crop farming carries risks that are often outside a farmer's control. Weather events, pests, crop failure and market changes can all affect production and farm income. Crop insurance is designed to provide a financial safety net when insured crops are damaged, destroyed or produce less than expected, helping farmers manage the business impact of an adverse season. - read more
Insurance is a vital part of safeguarding any farming operation. As a farmer, protecting your property, equipment, and livelihood from unexpected events like natural disasters, theft, or accidents is crucial. Adequate insurance coverage ensures that you can recover quickly from setbacks without enduring overwhelming financial strain. - read more
Choosing farm insurance starts with understanding the assets, activities and risks that make your farm different. From buildings and machinery to crops, livestock and liability exposures, the right policy structure depends on what you operate, what you own and how your farm could be affected by events such as storms, fire, theft, accidents or other disruptions. - read more
Australian farming businesses face liability risks that go well beyond crop production and livestock management. From visitor injuries and unsafe produce to chemical use, worker safety, machinery incidents and emerging technology risks, understanding where liability can arise is an important part of protecting a farm's long-term resilience. - read more
Farm insurance premiums are influenced by the type and level of cover you choose, the risks associated with your farming operation, your deductible or excess, and how accurately your policy reflects your current assets and activities. Saving money is not just about finding the lowest premium; it is about understanding what you are paying for and avoiding unnecessary gaps or duplicate cover. - read more
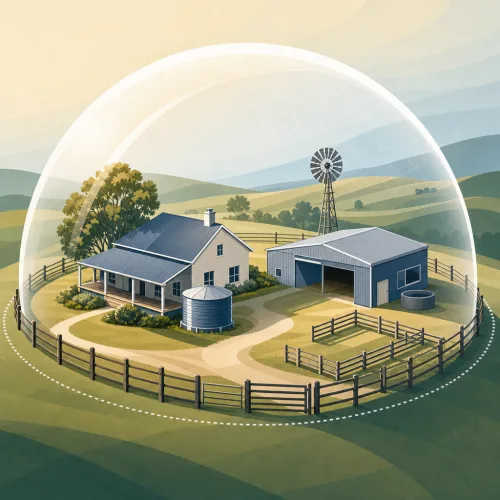
Farm property insurance can help protect the fixed assets on rural land, including farm buildings, sheds, fencing, tanks, yards and other infrastructure. This guide explains what may be covered, how values are usually reviewed and what details to check before comparing policy options. - read more
Need a Quote?
Start your free farm insurance quote comparison here.
Knowledgebase
Rider: An optional provision added to an insurance policy that provides additional benefits or coverage.
No comments yet. Be the first to share your thoughts.