
Zurich Welcomes Fresh Leadership in Risk Management for ANZ Region
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
In a dynamic move, Zurich Financial Services Australia has named David Wainwright as the new Chief Risk Officer for the Australia and New Zealand region.
This follows the retirement announcement of the current CRO, Jaimie Sach, a veteran with a distinguished 30-year career in the wealth management sector.
Wainwright's appointment signifies a strategic shift aimed at bolstering Zurich's risk management operations amid an evolving financial landscape. He transitions from Zurich's life insurance division in the United Kingdom, where he likewise served as Chief Risk Officer. His expansive expertise, honed through 25 years in financial services, positions Wainwright as a key asset for Zurich ANZ.
Justin Delaney, Zurich's Chief Executive, lauded Wainwright's arrival, stating, "Mr. Wainwright's international experience and strong technical and leadership skills will further strengthen our local risk management framework. We are eager to integrate his vision and expertise into our leadership team next year."
Wainwright's career is marked by prominent roles not only within Zurich UK but also at Nomura Securities, Halifax Bank of Scotland (HBOS), and HSBC Global Banking and Markets. This broad spectrum of experience underlines his ability to navigate and mitigate risk in complex financial environments.
Set to commence his new role on January 6, 2025, Wainwright will be relocating to Sydney, and will report directly to Sid Medappa, the Regional Head of Risk for the Asia Pacific (APAC) division at Zurich.
Expressing his enthusiasm for the forthcoming transition, Wainwright remarked, "I am thrilled to join the Zurich team in Australia and am dedicated to advancing our robust risk management capabilities."
As the legacy bearer of a rich 30-year career, Jaimie Sach has been steering Zurich's risk management since 2019. His departure marks the end of an illustrious chapter, paving the way for Wainwright to inject new perspectives and strategies into the ANZ regional risk operations.
This announcement underscores Zurich’s commitment to fortifying its risk management strategies in an environment increasingly characterized by financial complexities. Wainwright's appointment opens a new page in securing Zurich ANZ’s resilience and proactive risk management approach.
The source of this adaptation is an original article published by Newswire on Zurich's executive appointment.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
New workplace exposure limits for airborne contaminants are moving from a regulatory issue to a practical farm risk-management concern, particularly for grain growers heading through harvest. With the national transition scheduled for 1 December 2026, recent state decisions to delay or stage some limits have created a patchwork of obligations that farm businesses should watch closely. - read more
A recent Australian Financial Complaints Authority determination involving a flooded farmhouse has put claims handling back under the microscope for rural policyholders, after the insurer was ordered to pay almost $432,000 across building repairs, additional temporary accommodation, professional costs and compensation for non-financial loss. The decision, dated 27 August 2026 and reported by Insurance News on 15 October 2026, is a useful reminder that the practical aftermath of a farm flood can extend well beyond the first clean-up. - read more
Recent industry attention on insurance claims linked to ex-Tropical Cyclone Alfred is a timely reminder that severe weather losses rarely stop at damaged buildings. For farms across storm and flood-exposed regions, the real cost of an event can include cut access roads, damaged fencing, spoiled fodder, machinery downtime, livestock movement issues and weeks of operational disruption. - read more
Australia’s latest seasonal bushfire outlook is a practical reminder that fire risk is not confined to the height of summer. For many farms, the exposure begins well before a catastrophic fire day is declared, as grass growth, drying winds, stored fodder, machinery movement and access limitations combine to create a more complex risk profile than a standard rural home policy can address. - read more
Fresh industry concern about repair delays after severe weather is highly relevant for Australian farms, where a damaged shed, washed-out access track or unavailable part can quickly interrupt day-to-day operations. While the wider insurance discussion often focuses on homes and commercial buildings, the same pressure points can be even more complex on rural properties because assets are spread out, specialist equipment is involved and local contractor availability may be limited. - read more
Renewed industry pressure to reduce insurance taxes has put affordability back in the spotlight for rural and regional Australia. The latest debate centres on the extra costs added to insurance through state-based duties, levies and other charges, which can make already expensive cover harder to maintain for households and businesses exposed to flood, bushfire, storm and cyclone risk. - read more
Farm equipment insurance helps rural Australians manage the financial risk of damage, theft or loss involving essential agricultural machinery. Understanding what may be covered, what is commonly excluded and how claims are handled can make it easier to compare policies and keep cover aligned with changing farm operations. - read more
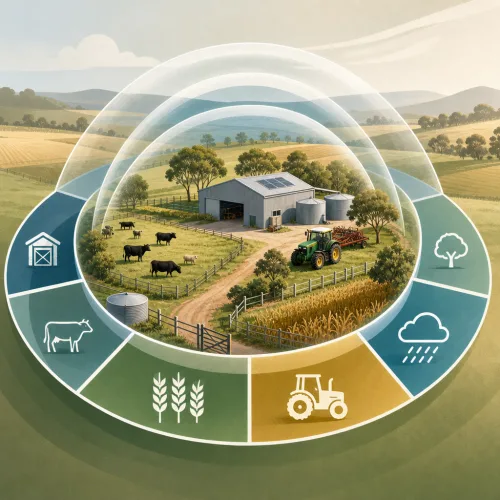
Farm insurance in Australia is usually built from several cover sections rather than one standard policy. This guide explains common inclusions, optional covers, limits and exclusions to check before comparing policies. - read more
Weather is one of the most important risk factors in Australian farming. Drought, flood, bushfire, cyclones, hail and heatwaves can affect crops, livestock, buildings, equipment and farm income. Because insurers assess these risks when pricing and structuring cover, understanding the link between weather and farm insurance can help farmers ask better questions when reviewing their policies. - read more
Choosing farm insurance starts with understanding the assets, activities and risks that make your farm different. From buildings and machinery to crops, livestock and liability exposures, the right policy structure depends on what you operate, what you own and how your farm could be affected by events such as storms, fire, theft, accidents or other disruptions. - read more
Farm insurance premiums are influenced by the type and level of cover you choose, the risks associated with your farming operation, your deductible or excess, and how accurately your policy reflects your current assets and activities. Saving money is not just about finding the lowest premium; it is about understanding what you are paying for and avoiding unnecessary gaps or duplicate cover. - read more
For Australian farmers, having the right insurance coverage isn't just a safety net—it's an integral part of sustaining their livelihood. Natural disasters, unpredictable climate conditions, and the inherent risks of agricultural production underline the critical importance of robust insurance for the agricultural community. As farmers navigate the complexities of insurance, understanding the basics becomes the first step toward securing their assets and ensuring the continuity of their operations. - read more
Need a Quote?
Start your free farm insurance quote comparison here.
Need a
FARM INSURANCE
QUOTE?
Knowledgebase
Beneficiary: The person or entity designated to receive the death benefit from a life insurance policy.
No comments yet. Be the first to share your thoughts.