
Home Parking Dilemma Leads to Insurance Dispute Loss
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
A homeowner's struggle with her narrow driveway has culminated in the rejection of her car theft claim, illustrating the critical importance of adhering to insurance policy stipulations.
The insurer, SGUAS, denied the claim based on a clause that excluded coverage for vehicles left on the street between 10pm and 5am. The woman's car was stolen at 2am from directly outside her house, with the thieves gaining access by breaking into her home and taking the keys.
According to a police report, the location of the car would not have deterred the thieves, who broke a window to enter the house. “Regardless of where the car was parked, the offenders would have successfully taken the vehicle," stated the report.
The car owner revealed that she bought her insurance through a broker and relied on him for managing all details. She admitted to frequently parking on the street because of the difficulty in maneuvering her car into the narrow driveway and carport of her new home.
During the investigation, her broker argued to the Australian Financial Complaints Authority (AFCA) that the car would have been stolen regardless of its parking spot. However, AFCA maintained that the insurer was not liable as the homeowner did not inform them of her regular street parking, a critical deviation from the declared parking arrangements.
AFCA's ombudsman expressed sympathy for the homeowner's plight but upheld the policy's exclusion for overnight street parking. "It seems this practice was established due to the inaccessible driveway, yet the policy clearly stipulates the necessity to inform the insurer of any such changes," the ombudsman noted.
"The homeowner consistently parked on the street overnight, thereby invalidating her insurance claim due to the policy's terms. The failure to communicate this change prejudiced the insurer’s ability to assess the risk properly, justifying the claim denial," the AFCA representative explained.
AFCA further noted that street parking significantly increases the risk of theft, a factor emphasized in the insurer’s underwriting guidelines. “Even though the thieves acted boldly, the information provided by the insurer indicates a higher theft risk for cars parked on the road,†it stated.
At the inception of the policy, the homeowner’s broker had conveyed detailed parking arrangements to the insurer, even providing a picture of the carport. Yet, this information became obsolete when the homeowner developed a habit of street parking without updating the insurer.
This case serves as a stark reminder of the crucial role precise adherence to insurance policy terms plays. Policyholders should communicate any changes in their circumstances to ensure their coverage remains valid. For more details, you can refer to the original ruling by AFCA.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
New workplace exposure limits for airborne contaminants are moving from a regulatory issue to a practical farm risk-management concern, particularly for grain growers heading through harvest. With the national transition scheduled for 1 December 2026, recent state decisions to delay or stage some limits have created a patchwork of obligations that farm businesses should watch closely. - read more
A recent Australian Financial Complaints Authority determination involving a flooded farmhouse has put claims handling back under the microscope for rural policyholders, after the insurer was ordered to pay almost $432,000 across building repairs, additional temporary accommodation, professional costs and compensation for non-financial loss. The decision, dated 27 August 2026 and reported by Insurance News on 15 October 2026, is a useful reminder that the practical aftermath of a farm flood can extend well beyond the first clean-up. - read more
Recent industry attention on insurance claims linked to ex-Tropical Cyclone Alfred is a timely reminder that severe weather losses rarely stop at damaged buildings. For farms across storm and flood-exposed regions, the real cost of an event can include cut access roads, damaged fencing, spoiled fodder, machinery downtime, livestock movement issues and weeks of operational disruption. - read more
Australia’s latest seasonal bushfire outlook is a practical reminder that fire risk is not confined to the height of summer. For many farms, the exposure begins well before a catastrophic fire day is declared, as grass growth, drying winds, stored fodder, machinery movement and access limitations combine to create a more complex risk profile than a standard rural home policy can address. - read more
Fresh industry concern about repair delays after severe weather is highly relevant for Australian farms, where a damaged shed, washed-out access track or unavailable part can quickly interrupt day-to-day operations. While the wider insurance discussion often focuses on homes and commercial buildings, the same pressure points can be even more complex on rural properties because assets are spread out, specialist equipment is involved and local contractor availability may be limited. - read more
Renewed industry pressure to reduce insurance taxes has put affordability back in the spotlight for rural and regional Australia. The latest debate centres on the extra costs added to insurance through state-based duties, levies and other charges, which can make already expensive cover harder to maintain for households and businesses exposed to flood, bushfire, storm and cyclone risk. - read more
The world of farming is one filled with uncertainties. Weather conditions, market prices, and various other factors can create a highly volatile income stream for those within the agricultural sector. This unpredictability can lead to financial instability that impacts not only the farmers themselves but also their families and the larger rural community. - read more
For Australian farmers, having the right insurance coverage isn't just a safety net—it's an integral part of sustaining their livelihood. Natural disasters, unpredictable climate conditions, and the inherent risks of agricultural production underline the critical importance of robust insurance for the agricultural community. As farmers navigate the complexities of insurance, understanding the basics becomes the first step toward securing their assets and ensuring the continuity of their operations. - read more
Choosing farm insurance starts with understanding the assets, activities and risks that make your farm different. From buildings and machinery to crops, livestock and liability exposures, the right policy structure depends on what you operate, what you own and how your farm could be affected by events such as storms, fire, theft, accidents or other disruptions. - read more
Farm succession is the planned transfer of farm ownership, management and knowledge from one generation to the next. For rural Australian families, it can involve complex family, legal, financial and operational decisions, so starting early and using a structured process can help reduce uncertainty. - read more
Farm property insurance can help protect the fixed assets on rural land, including farm buildings, sheds, fencing, tanks, yards and other infrastructure. This guide explains what may be covered, how values are usually reviewed and what details to check before comparing policy options. - read more
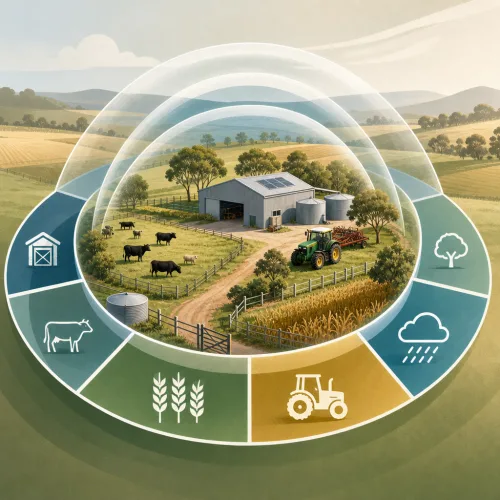
Farm insurance in Australia is usually built from several cover sections rather than one standard policy. This guide explains common inclusions, optional covers, limits and exclusions to check before comparing policies. - read more
Need a Quote?
Start your free farm insurance quote comparison here.
Need a
FARM INSURANCE
QUOTE?
Knowledgebase
Income Insurance: Insures your income in the event of you being unable to work due to sickness or accident.
No comments yet. Be the first to share your thoughts.