

AFCA Rebukes IAG Over Mismanaged Flood Damage Claim
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Insurance Australia Group (IAG) has been mandated to reexamine a denied claim and offer compensation to a driver whose "vulnerable status" was overlooked.
Following a flood incident in remote Northern Territory, the driver submitted a claim on March 9 last year after his car was trapped in the floodwaters. He was transporting a friend to retrieve her vehicle when the floodwater immobilized his Holden Commodore, valued at $32,000.
The driver reported significant water intrusion into the vehicle, compromising its engine and electronics. He and his passenger needed over 15 minutes to push the vehicle out from the water.
IAG arranged for the car to be transported to Darwin for inspection. In June, the mechanic’s report indicated no water damage to the engine or interior, yet traces of water were discovered in its oil.
Another mechanic’s assessment found no water in the air filters or throttle but noted rust corrosion, indicative of water presence.
Due to the claim being filed six days after the policy initiation, IAG flagged the claim's legitimacy and handed it over to their fraud investigation unit. The unit interviewed both the driver and passenger and demanded multiple documents, including mobile records, a car purchase contract, and service history.
According to the Australian Financial Complaints Authority (AFCA), the driver submitted all requested documentation with the exception of his bank statements. Unfortunately, his mobile phone records were not provided in the correct format.
The insurer contended that further investigation was contingent on receiving all requested information and upheld their decision to decline the claim pending additional data.
However, AFCA challenged IAG’s stance, arguing the driver had sufficiently complied with the investigation despite the missing documentation. The authority stated that evidence from the two expert reports supported the driver’s account of events.
The authority emphasized the presence of water in the vehicle, citing the seized engine, evident corrosion in all cylinders, the presence of surface rust, and the milky oil in the oil filter, all hinting at water contamination.
Additionally, AFCA criticized IAG for not recognizing the driver’s vulnerability, stemming from his remote residence, financial duress, and health issues, including a broken leg.
AFCA noted that the insurer's mishandling of the claim had caused avoidable stress and delays for the driver. Consequentially, IAG was compelled to pay a penalty of $5400 for non-financial losses.
"The insurer should either properly execute its investigation or make a claim decision based on the available information," AFCA stated. "Unreasonable demands for additional information have resulted in undue stress for the claimant. IAG must compensate him for the resulting inconvenience and emotional distress."
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
Recent industry attention on insurance claims linked to ex-Tropical Cyclone Alfred is a timely reminder that severe weather losses rarely stop at damaged buildings. For farms across storm and flood-exposed regions, the real cost of an event can include cut access roads, damaged fencing, spoiled fodder, machinery downtime, livestock movement issues and weeks of operational disruption. - read more
Australia’s latest seasonal bushfire outlook is a practical reminder that fire risk is not confined to the height of summer. For many farms, the exposure begins well before a catastrophic fire day is declared, as grass growth, drying winds, stored fodder, machinery movement and access limitations combine to create a more complex risk profile than a standard rural home policy can address. - read more
Fresh industry concern about repair delays after severe weather is highly relevant for Australian farms, where a damaged shed, washed-out access track or unavailable part can quickly interrupt day-to-day operations. While the wider insurance discussion often focuses on homes and commercial buildings, the same pressure points can be even more complex on rural properties because assets are spread out, specialist equipment is involved and local contractor availability may be limited. - read more
Renewed industry pressure to reduce insurance taxes has put affordability back in the spotlight for rural and regional Australia. The latest debate centres on the extra costs added to insurance through state-based duties, levies and other charges, which can make already expensive cover harder to maintain for households and businesses exposed to flood, bushfire, storm and cyclone risk. - read more
Recent complaints data from the Australian Financial Complaints Authority has again highlighted a pressure point that matters to rural Australia: insurance claims can become difficult when expectations, policy wording and evidence do not line up. While the figures cover the wider insurance market rather than farms alone, the themes are highly relevant for agricultural businesses dealing with storm damage, fire losses, machinery failures, fencing repairs or interrupted operations. - read more
Australia's latest seasonal weather signals have again pushed rainfall risk into the foreground for rural and regional businesses. While conditions vary sharply between districts, a wetter outlook for parts of the country is a useful reminder that risk planning should not wait until paddocks are already saturated, creek crossings are cut or machinery is bogged at harvest. - read more
Farm insurance is an important part of managing agricultural risk, but premiums still need to fit the realities of farm cash flow. This guide explains practical ways Australian farmers can review cover, reduce avoidable costs and keep insurance aligned with the risks, assets and operations on their farm. - read more
Welcome to 'The Ultimate Guide to Affordable Farm Insurance for Australian Farmers.' As stewards of the vast Australian countryside, farmers face an array of unique challenges and risks. Every day, they grapple with the forces of nature, the volatility of the markets, and the complexities of modern agricultural operations. - read more
Weather is one of the most important risk factors in Australian farming. Drought, flood, bushfire, cyclones, hail and heatwaves can affect crops, livestock, buildings, equipment and farm income. Because insurers assess these risks when pricing and structuring cover, understanding the link between weather and farm insurance can help farmers ask better questions when reviewing their policies. - read more
For Australian farmers, having the right insurance coverage isn't just a safety net—it's an integral part of sustaining their livelihood. Natural disasters, unpredictable climate conditions, and the inherent risks of agricultural production underline the critical importance of robust insurance for the agricultural community. As farmers navigate the complexities of insurance, understanding the basics becomes the first step toward securing their assets and ensuring the continuity of their operations. - read more
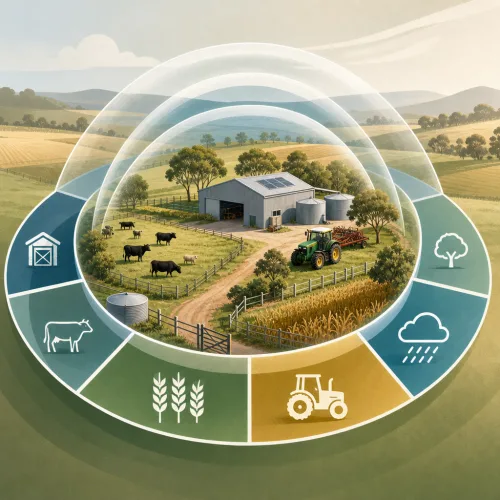
Farm insurance in Australia is usually built from several cover sections rather than one standard policy. This guide explains common inclusions, optional covers, limits and exclusions to check before comparing policies. - read more
Whether you're a seasoned farmer or just starting out, understanding farm insurance is crucial. It's more than just a safety net; it's a way to ensure that your farming business can withstand unforeseen challenges. By safeguarding your livelihood, farm insurance offers peace of mind amidst uncertainties. - read more
Need a Quote?
Start your free farm insurance quote comparison here.
Knowledgebase
Insurance Deductible: That part of an insurance claim that must be paid by an insured person before the the balance is paid by the insurer.
No comments yet. Be the first to share your thoughts.