
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
A claimant's bank funds have been frozen following accusations of fraudulent activities involving counterfeit medical invoices.
The civil lawsuit, initiated by NRMA Insurance, targets Haneen Asfour, who is accused of securing funds through false pretenses. The insurer alleges that Asfour accumulated $380,594 through deceptive claims.
After a car accident in Prospect in December 2022, Asfour began receiving statutory benefits from NRMA. However, additional payments were requested for private medical treatments that, according to sworn testimonies from medical practitioners, were never provided.
The extreme measure of halting Asfour’s financial transactions was deemed necessary by a NSW Supreme Court judge, who expressed the likelihood of Asfour potentially diverting or disposing of the misappropriated funds.
The court’s decision is rooted in claims that, without the order, Asfour could easily deplete the alleged fraudulent funds by various means such as withdrawing from bank accounts or transferring assets to more obscure locations.
NRMA's legal team claims that the fraudulent activities were apparent and purposeful, aimed at exploiting the insurer’s funding for private pain management and therapy sessions that did not occur.
The freezing order and NRMA’s statement of claim were formally presented to Asfour last week. Nonetheless, she will continue to receive her statutory payments of $2113 fortnightly, after tax deductions, amid ongoing investigations.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
A recent Australian Financial Complaints Authority determination involving a flooded farmhouse has put claims handling back under the microscope for rural policyholders, after the insurer was ordered to pay almost $432,000 across building repairs, additional temporary accommodation, professional costs and compensation for non-financial loss. The decision, dated 27 August 2026 and reported by Insurance News on 15 October 2026, is a useful reminder that the practical aftermath of a farm flood can extend well beyond the first clean-up. - read more
Recent industry attention on insurance claims linked to ex-Tropical Cyclone Alfred is a timely reminder that severe weather losses rarely stop at damaged buildings. For farms across storm and flood-exposed regions, the real cost of an event can include cut access roads, damaged fencing, spoiled fodder, machinery downtime, livestock movement issues and weeks of operational disruption. - read more
Australia’s latest seasonal bushfire outlook is a practical reminder that fire risk is not confined to the height of summer. For many farms, the exposure begins well before a catastrophic fire day is declared, as grass growth, drying winds, stored fodder, machinery movement and access limitations combine to create a more complex risk profile than a standard rural home policy can address. - read more
Fresh industry concern about repair delays after severe weather is highly relevant for Australian farms, where a damaged shed, washed-out access track or unavailable part can quickly interrupt day-to-day operations. While the wider insurance discussion often focuses on homes and commercial buildings, the same pressure points can be even more complex on rural properties because assets are spread out, specialist equipment is involved and local contractor availability may be limited. - read more
Renewed industry pressure to reduce insurance taxes has put affordability back in the spotlight for rural and regional Australia. The latest debate centres on the extra costs added to insurance through state-based duties, levies and other charges, which can make already expensive cover harder to maintain for households and businesses exposed to flood, bushfire, storm and cyclone risk. - read more
Recent complaints data from the Australian Financial Complaints Authority has again highlighted a pressure point that matters to rural Australia: insurance claims can become difficult when expectations, policy wording and evidence do not line up. While the figures cover the wider insurance market rather than farms alone, the themes are highly relevant for agricultural businesses dealing with storm damage, fire losses, machinery failures, fencing repairs or interrupted operations. - read more
The threat of bushfires looms large over the vast expanses of rural Australia, shaping the reality of farming in this sunbaked landscape. The risk, always present, escalates as the climate warms and dry conditions persist. It's not a matter of if, but when the land will be tested by fire's wrath. In this environment, the armor of insurance isn't just recommended; it's critical for survival. - read more
Farm succession is the planned transfer of farm ownership, management and knowledge from one generation to the next. For rural Australian families, it can involve complex family, legal, financial and operational decisions, so starting early and using a structured process can help reduce uncertainty. - read more
Weather is one of the most important risk factors in Australian farming. Drought, flood, bushfire, cyclones, hail and heatwaves can affect crops, livestock, buildings, equipment and farm income. Because insurers assess these risks when pricing and structuring cover, understanding the link between weather and farm insurance can help farmers ask better questions when reviewing their policies. - read more
Farm equipment insurance helps rural Australians manage the financial risk of damage, theft or loss involving essential agricultural machinery. Understanding what may be covered, what is commonly excluded and how claims are handled can make it easier to compare policies and keep cover aligned with changing farm operations. - read more
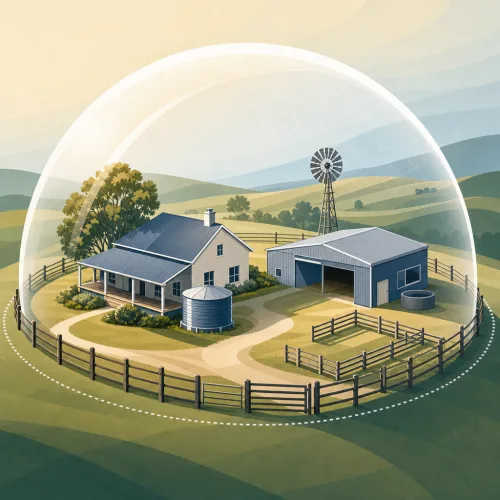
Farm property insurance can help protect the fixed assets on rural land, including farm buildings, sheds, fencing, tanks, yards and other infrastructure. This guide explains what may be covered, how values are usually reviewed and what details to check before comparing policy options. - read more
Whether you're a seasoned farmer or just starting out, understanding farm insurance is crucial. It's more than just a safety net; it's a way to ensure that your farming business can withstand unforeseen challenges. By safeguarding your livelihood, farm insurance offers peace of mind amidst uncertainties. - read more
Need a Quote?
Start your free farm insurance quote comparison here.
Knowledgebase
Disability Insurance: A type of insurance protection that pays a portion of a person's income lost due to a total or partial disablement arising from either an accident or a sickness.
No comments yet. Be the first to share your thoughts.