Farm Insurance :: Articles

Insurance Disputes

How can I challenge my insurance claim rejection if I feel it was unfair?

Insurance Disputes

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Just because your insurer has rejected your claim, does not necessarily mean that your case is closed. If you think that you have been unfairly treated, here are some ways to get the insurer decision overturned.

What to do

  • Inform the insurance company as soon as you can following the event. It is sometimes a good idea to write the details of the event as soon as you can, and then use that as a reference to make the written claim.
  • Be consistent. Remember, it will be awkward if you want to change your story later on.
  • Keep all documents that are relevant to the claim.
  • Make sure the staff of the insurance company can get in touch with you.

If the claim is rejected?

There are circumstances where you may in fact have the legal right to be reimbursed for your loss even though the insurer refused to pay the claim. Although you can sometimes make this judgement yourself, it is sometimes a good idea to get legal advice. See our fact sheets on "Disputes".

Check the policy

If the claim is rejected ask your insurer to identify specifically the clause of the contract on which they rely. If you do not have a current policy make sure they supply one.

What caused the loss?

If the insurer claims that you caused the loss, and this is in breach of the policy, make sure that this is so.
For instance, if you were smoking in bed at the time of a fire, and a fire caused this way is a breach of your policy, you may not in fact be in breach if the fire was caused by an electrical fault. In this case the fact that you were smoking in bed would be coincidental and not the cause of the fire.

Pre-existing conditions

The policy may stipulate that a known pre-existing situation or condition is not covered. For instance, if you have disability insurance but at the time you signed the policy you had a tumor. However, under the law it would be crucial whether you actually knew you had this condition. If you were unaware of it you should still be covered.

Ignorance of the terms

Under the law the insurer has a legal obligation to inform you about the restrictions in the insurance policy. This must be done before you sign the application and the policy is issued. This means (in part) that:
  • you must be given a copy of the policy; and
  • the wording of the policy must be clear and unambiguous.
If these pre-conditions were not met it may be possible to retain your coverage for your loss. Again, it may be necessary to obtain legal advice.

Is it worth the claim?

Many types of insurance contracts will have an excess. This is common in a car insurance contract, or similarly you may lose part of the no-claims bonus. Some companies now reward rating one drivers with a lifetime rating one guarantee. At times you will have to decide whether the amount of the claim is worth the long term loss that results from the effect on rating or no-claims bonuses, especially after taking into account the amount of the excess.

Published: Sunday, 1st Aug 2021
Author: Paige Estritori

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Insurance News

New Dust Limits Put Farm Safety Records in the Insurance Spotlight
04 Nov 2026: Paige Estritori
New workplace exposure limits for airborne contaminants are moving from a regulatory issue to a practical farm risk-management concern, particularly for grain growers heading through harvest. With the national transition scheduled for 1 December 2026, recent state decisions to delay or stage some limits have created a patchwork of obligations that farm businesses should watch closely. - read more
Farm Flood Dispute Shows the Cost of Delayed Claims Handling
28 Oct 2026: Paige Estritori
A recent Australian Financial Complaints Authority determination involving a flooded farmhouse has put claims handling back under the microscope for rural policyholders, after the insurer was ordered to pay almost $432,000 across building repairs, additional temporary accommodation, professional costs and compensation for non-financial loss. The decision, dated 27 August 2026 and reported by Insurance News on 15 October 2026, is a useful reminder that the practical aftermath of a farm flood can extend well beyond the first clean-up. - read more
What Cyclone Alfred Recovery Teaches Farmers About Insurance
16 Sep 2026: Paige Estritori
Recent industry attention on insurance claims linked to ex-Tropical Cyclone Alfred is a timely reminder that severe weather losses rarely stop at damaged buildings. For farms across storm and flood-exposed regions, the real cost of an event can include cut access roads, damaged fencing, spoiled fodder, machinery downtime, livestock movement issues and weeks of operational disruption. - read more
Seasonal Bushfire Risk Puts Farm Cover Back in the Spotlight
09 Sep 2026: Paige Estritori
Australia’s latest seasonal bushfire outlook is a practical reminder that fire risk is not confined to the height of summer. For many farms, the exposure begins well before a catastrophic fire day is declared, as grass growth, drying winds, stored fodder, machinery movement and access limitations combine to create a more complex risk profile than a standard rural home policy can address. - read more
Why Repair Bottlenecks Matter for Farm Insurance Claims
02 Sep 2026: Paige Estritori
Fresh industry concern about repair delays after severe weather is highly relevant for Australian farms, where a damaged shed, washed-out access track or unavailable part can quickly interrupt day-to-day operations. While the wider insurance discussion often focuses on homes and commercial buildings, the same pressure points can be even more complex on rural properties because assets are spread out, specialist equipment is involved and local contractor availability may be limited. - read more
Insurance Tax Debate Puts Farm Premiums Back in Focus
26 Aug 2026: Paige Estritori
Renewed industry pressure to reduce insurance taxes has put affordability back in the spotlight for rural and regional Australia. The latest debate centres on the extra costs added to insurance through state-based duties, levies and other charges, which can make already expensive cover harder to maintain for households and businesses exposed to flood, bushfire, storm and cyclone risk. - read more

Farm Insurance Articles

Common Myths About Farm Insurance Debunked
Whether you're a seasoned farmer or just starting out, understanding farm insurance is crucial. It's more than just a safety net; it's a way to ensure that your farming business can withstand unforeseen challenges. By safeguarding your livelihood, farm insurance offers peace of mind amidst uncertainties. - read more
Financial Planning for Australian Farmers During Persistent Drought
Persistent drought can place sustained pressure on Australian farm income, cash flow, livestock management, crop production and long-term investment decisions. A practical drought financial plan can help farm owners assess risks, control costs, preserve flexibility and make more informed decisions during extended dry periods. - read more
Livestock Insurance for Australian Farmers: What to Know Before Choosing Cover
Livestock insurance can help Australian farmers manage the financial impact of unexpected animal losses caused by events such as disease, accidental death, theft, transit incidents or extreme weather. The right policy settings depend on the type of livestock, the risks faced by the farm, how animals are valued and the exclusions that apply. - read more
Farm Business Interruption Insurance and Loss of Income Cover Explained
Farm business interruption insurance may help protect farm income and cover certain extra costs when an insured event disrupts operations. This guide explains how it works, what it may cover, where it differs from personal income protection and crop insurance, and what to check before relying on it. - read more
The Farmer's Handbook to Quick and Effective Insurance Claims
Insurance is a vital part of safeguarding any farming operation. As a farmer, protecting your property, equipment, and livelihood from unexpected events like natural disasters, theft, or accidents is crucial. Adequate insurance coverage ensures that you can recover quickly from setbacks without enduring overwhelming financial strain. - read more
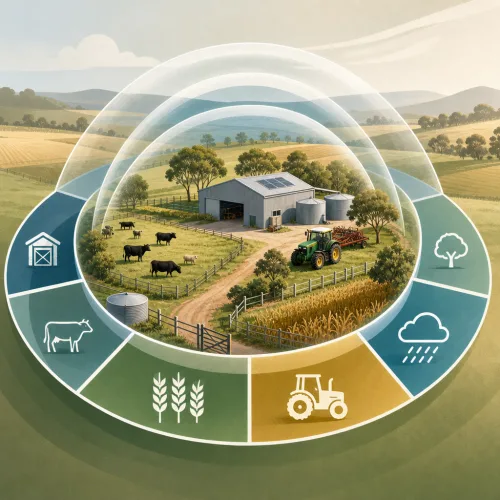
What Does Farm Insurance Cover in Australia?
Farm insurance in Australia is usually built from several cover sections rather than one standard policy. This guide explains common inclusions, optional covers, limits and exclusions to check before comparing policies. - read more

Need a Quote?
Start your free farm insurance quote comparison here.

Start Here ...

Farm Type:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.

Need a
FARM INSURANCE
QUOTE?

Knowledgebase
Peril:
A specific risk or cause of loss covered by an insurance policy, such as fire, theft, or flood.