
Bakery Blaze Sparks Allegations of Insurance Fraud
The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
A bakery owner in Western Australia has been engulfed in controversy following accusations of deliberately setting her business premises on fire.
Officials allege this was an attempt to secure a hefty insurance payout.
The establishment, located in Spencer Park, Albany, suffered extensive roof and structural damage during the blaze on October 12. Concerningly, the damage bill has climbed to an estimated $955,000.
Law enforcement officials assert that the bakery owner intentionally ignited the fire and subsequently filed an insurance claim to compensate for the losses incurred. The insurance policy in question apparently included coverage for up to $500,000 in contents, as well as an enormous $2.2 million for lost business income due to interruption.
Charged with both criminal damage by fire and fraudulent attempts to gain financial benefits, the owner is set to face legal proceedings. Her appearance before the Albany Magistrates’ Court is scheduled for December 12.
This case highlights a critical issue often faced in the insurance industry—the persistent problem of insurance fraud. Notably, cases like these not only undermine trust but also inflate insurance premiums, impacting honest business proprietors nationwide.
In the unfortunate event of genuine fires, insurers generally process numerous legitimate claims annually. However, each fraudulent claim burdens the system, leading to losses shared among honest policyholders through increased rates.
This alleged incident in Albany draws parallels to previous notorious cases in which business proprietors have been found culpable. Not much long ago, a bakery incident in Perth saw a business owner sentenced to community service after attempting to claim insurance following a suspicious fire.
Such happenings remind stakeholders in the financial and insurance sectors of the need to substantiate claims thoroughly and exercise vigilance. As investigations continue in the Albany case, the industry watches closely while hoping for a resolution that underscores the importance of integrity and transparency in business operations.
According to a report by local media, the alleged actions of the bakery owner raise serious questions about ethical conduct and business responsibility. The final court verdict will undoubtedly be pivotal in addressing these pressing matters.
Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.
Recent industry attention on insurance claims linked to ex-Tropical Cyclone Alfred is a timely reminder that severe weather losses rarely stop at damaged buildings. For farms across storm and flood-exposed regions, the real cost of an event can include cut access roads, damaged fencing, spoiled fodder, machinery downtime, livestock movement issues and weeks of operational disruption. - read more
Australia’s latest seasonal bushfire outlook is a practical reminder that fire risk is not confined to the height of summer. For many farms, the exposure begins well before a catastrophic fire day is declared, as grass growth, drying winds, stored fodder, machinery movement and access limitations combine to create a more complex risk profile than a standard rural home policy can address. - read more
Fresh industry concern about repair delays after severe weather is highly relevant for Australian farms, where a damaged shed, washed-out access track or unavailable part can quickly interrupt day-to-day operations. While the wider insurance discussion often focuses on homes and commercial buildings, the same pressure points can be even more complex on rural properties because assets are spread out, specialist equipment is involved and local contractor availability may be limited. - read more
Renewed industry pressure to reduce insurance taxes has put affordability back in the spotlight for rural and regional Australia. The latest debate centres on the extra costs added to insurance through state-based duties, levies and other charges, which can make already expensive cover harder to maintain for households and businesses exposed to flood, bushfire, storm and cyclone risk. - read more
Recent complaints data from the Australian Financial Complaints Authority has again highlighted a pressure point that matters to rural Australia: insurance claims can become difficult when expectations, policy wording and evidence do not line up. While the figures cover the wider insurance market rather than farms alone, the themes are highly relevant for agricultural businesses dealing with storm damage, fire losses, machinery failures, fencing repairs or interrupted operations. - read more
Australia's latest seasonal weather signals have again pushed rainfall risk into the foreground for rural and regional businesses. While conditions vary sharply between districts, a wetter outlook for parts of the country is a useful reminder that risk planning should not wait until paddocks are already saturated, creek crossings are cut or machinery is bogged at harvest. - read more
Welcome to 'The Ultimate Guide to Affordable Farm Insurance for Australian Farmers.' As stewards of the vast Australian countryside, farmers face an array of unique challenges and risks. Every day, they grapple with the forces of nature, the volatility of the markets, and the complexities of modern agricultural operations. - read more
The world of farming is one filled with uncertainties. Weather conditions, market prices, and various other factors can create a highly volatile income stream for those within the agricultural sector. This unpredictability can lead to financial instability that impacts not only the farmers themselves but also their families and the larger rural community. - read more
Whether you're a seasoned farmer or just starting out, understanding farm insurance is crucial. It's more than just a safety net; it's a way to ensure that your farming business can withstand unforeseen challenges. By safeguarding your livelihood, farm insurance offers peace of mind amidst uncertainties. - read more
In the ever-evolving landscape of modern agriculture, the security and stability of a farm hinge on thorough preparation and strategic foresight. A pivotal component in safeguarding a farm's future lies in the critical role of on-farm risk assessment. This process provides a structured approach to identifying potential risks that could affect a farm's operations, financial health, and overall sustainability. - read more
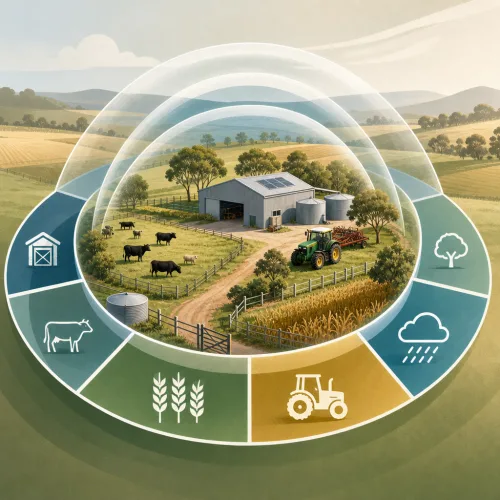
Farm insurance in Australia is usually built from several cover sections rather than one standard policy. This guide explains common inclusions, optional covers, limits and exclusions to check before comparing policies. - read more
For Australian farmers, having the right insurance coverage isn't just a safety net—it's an integral part of sustaining their livelihood. Natural disasters, unpredictable climate conditions, and the inherent risks of agricultural production underline the critical importance of robust insurance for the agricultural community. As farmers navigate the complexities of insurance, understanding the basics becomes the first step toward securing their assets and ensuring the continuity of their operations. - read more
Need a Quote?
Start your free farm insurance quote comparison here.
Knowledgebase
Double Indemnity: A clause or provision in a life insurance policy that doubles the payout in cases of accidental death.
No comments yet. Be the first to share your thoughts.