
Farm Insurance :: News
SHARE

Share this news item!

What Cyclone Alfred Recovery Teaches Farmers About Insurance

Severe weather claims show why cover needs to match real farm disruption

What Cyclone Alfred Recovery Teaches Farmers About Insurance?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Recent industry attention on insurance claims linked to ex-Tropical Cyclone Alfred is a timely reminder that severe weather losses rarely stop at damaged buildings.
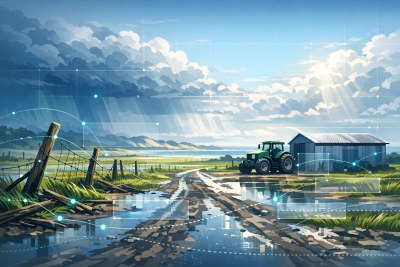
For farms across storm and flood-exposed regions, the real cost of an event can include cut access roads, damaged fencing, spoiled fodder, machinery downtime, livestock movement issues and weeks of operational disruption.

While Cyclone Alfred was unusual in its track and impact, the insurance lesson is familiar. A single weather system can trigger multiple types of loss across one rural property. Wind may affect sheds and roofing, surface water may damage stored equipment, fallen trees may bring down fences, and power interruptions may compromise refrigeration, pumps or automated systems. Whether those losses are covered depends on the wording, the sections selected and any exclusions or sub-limits that apply.

For farm operators, the first practical step is to separate weather risk into categories. Storm, flood, accidental damage, machinery breakdown, livestock losses and business interruption cover are not always treated the same way. Flood in particular can be defined narrowly, and some policies may exclude it unless it is specifically included. Farmers should also check whether fencing, laneways, pumps, tanks, silos and other fixed improvements are listed accurately enough to support a claim.

The second lesson is documentation. After a major weather event, insurers will usually need clear evidence of what was damaged, when it occurred and what it will cost to repair or replace. Up-to-date asset registers, photos, invoices, livestock records and maintenance notes can make a significant difference, especially where damage is spread across several paddocks or blocks.

There is also a cash-flow angle. Even where cover responds, rural repairs can take time because contractors, parts and assessors may be stretched across a wide affected area. Farms that rely on a damaged shed, access track, irrigation system or piece of equipment may need to plan for temporary workarounds while the claim progresses.

Rather than waiting for the next cyclone, flood or severe storm warning, farmers can use this recovery period as a prompt to review values, exclusions, excesses and waiting periods. It is also worth asking whether current sums insured reflect today’s rebuilding and replacement costs, not old purchase prices.

As weather volatility keeps testing rural Australia, the strongest insurance position is usually built before the claim. That means understanding the policy, keeping evidence current, and taking time to compare policy options against the actual assets and activities on the farm.

Published:Wednesday, 16th Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

What Cyclone Alfred Recovery Teaches Farmers About Insurance
16 Sep 2026: Paige Estritori
Recent industry attention on insurance claims linked to ex-Tropical Cyclone Alfred is a timely reminder that severe weather losses rarely stop at damaged buildings. For farms across storm and flood-exposed regions, the real cost of an event can include cut access roads, damaged fencing, spoiled fodder, machinery downtime, livestock movement issues and weeks of operational disruption. - read more
Seasonal Bushfire Risk Puts Farm Cover Back in the Spotlight
09 Sep 2026: Paige Estritori
Australia’s latest seasonal bushfire outlook is a practical reminder that fire risk is not confined to the height of summer. For many farms, the exposure begins well before a catastrophic fire day is declared, as grass growth, drying winds, stored fodder, machinery movement and access limitations combine to create a more complex risk profile than a standard rural home policy can address. - read more
Why Repair Bottlenecks Matter for Farm Insurance Claims
02 Sep 2026: Paige Estritori
Fresh industry concern about repair delays after severe weather is highly relevant for Australian farms, where a damaged shed, washed-out access track or unavailable part can quickly interrupt day-to-day operations. While the wider insurance discussion often focuses on homes and commercial buildings, the same pressure points can be even more complex on rural properties because assets are spread out, specialist equipment is involved and local contractor availability may be limited. - read more
Insurance Tax Debate Puts Farm Premiums Back in Focus
26 Aug 2026: Paige Estritori
Renewed industry pressure to reduce insurance taxes has put affordability back in the spotlight for rural and regional Australia. The latest debate centres on the extra costs added to insurance through state-based duties, levies and other charges, which can make already expensive cover harder to maintain for households and businesses exposed to flood, bushfire, storm and cyclone risk. - read more
Why Claims Disputes Should Prompt a Farm Insurance Review
19 Aug 2026: Paige Estritori
Recent complaints data from the Australian Financial Complaints Authority has again highlighted a pressure point that matters to rural Australia: insurance claims can become difficult when expectations, policy wording and evidence do not line up. While the figures cover the wider insurance market rather than farms alone, the themes are highly relevant for agricultural businesses dealing with storm damage, fire losses, machinery failures, fencing repairs or interrupted operations. - read more
Wetter Weather Forecast Puts Rural Cover Under the Microscope
12 Aug 2026: Paige Estritori
Australia's latest seasonal weather signals have again pushed rainfall risk into the foreground for rural and regional businesses. While conditions vary sharply between districts, a wetter outlook for parts of the country is a useful reminder that risk planning should not wait until paddocks are already saturated, creek crossings are cut or machinery is bogged at harvest. - read more


Farm Insurance Articles

Farm Business Interruption Insurance and Loss of Income Cover Explained
Farm business interruption insurance may help protect farm income and cover certain extra costs when an insured event disrupts operations. This guide explains how it works, what it may cover, where it differs from personal income protection and crop insurance, and what to check before relying on it. - read more
Financial Planning for Australian Farmers During Persistent Drought
Persistent drought can place sustained pressure on Australian farm income, cash flow, livestock management, crop production and long-term investment decisions. A practical drought financial plan can help farm owners assess risks, control costs, preserve flexibility and make more informed decisions during extended dry periods. - read more
The Farmer's Handbook to Quick and Effective Insurance Claims
Insurance is a vital part of safeguarding any farming operation. As a farmer, protecting your property, equipment, and livelihood from unexpected events like natural disasters, theft, or accidents is crucial. Adequate insurance coverage ensures that you can recover quickly from setbacks without enduring overwhelming financial strain. - read more
Income Protection Insurance for Hobby Farmers: What to Consider
Hobby farming may not be your main source of income, but it can still be financially important. If illness or injury prevents you from working, income protection insurance may help replace part of your income while you recover, depending on the policy terms. - read more
How to Choose the Right Farm Insurance Policy for Your Farm
Choosing farm insurance starts with understanding the assets, activities and risks that make your farm different. From buildings and machinery to crops, livestock and liability exposures, the right policy structure depends on what you operate, what you own and how your farm could be affected by events such as storms, fire, theft, accidents or other disruptions. - read more
Agribusiness Liability Risks Facing Australian Farmers
Australian farming businesses face liability risks that go well beyond crop production and livestock management. From visitor injuries and unsafe produce to chemical use, worker safety, machinery incidents and emerging technology risks, understanding where liability can arise is an important part of protecting a farm's long-term resilience. - read more

Need a Quote?
Start your free farm insurance quote comparison here.
Farm Type:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.


Knowledgebase
Grace Period:
A time period after the premium is due during which an insurance policy remains in force even if the premium has not yet been paid.