
Farm Insurance :: News
SHARE

Share this news item!

Storm Damage Brings a Fresh Claims Warning for Farmers

Queensland and NSW storms show why repair approvals and evidence matter

Storm Damage Brings a Fresh Claims Warning for Farmers?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

A fresh Insurance Council of Australia warning about disaster chasers after the Queensland and New South Wales storms is highly relevant for farm businesses now moving from clean-up to claims.
On 18 November 2026, the council said more than 9,000 claims had been lodged after severe weather across the two states from 11-17 November, with some operators allegedly approaching damaged properties and pushing repair work before insurers have approved it.

The immediate insurance issue is not only the storm damage itself. For farms, the risk is that urgent repairs to roofs, fencing, sheds, pumps, cool rooms, worker accommodation or access infrastructure may be arranged under pressure, without clear authority, proper records or an understanding of what the policy will actually reimburse. That can turn a difficult claim into a dispute over scope, pricing or whether the work was reasonable.

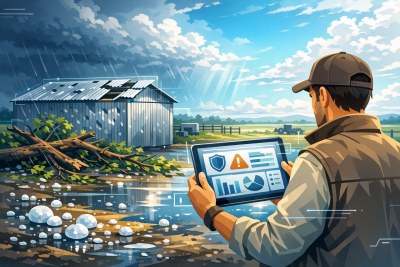
The earlier declaration for the event, known as SE265, had already been extended to capture storms across both states. Reported damage included torn roofs, destroyed fences, water entry, hail impacts and food spoilage linked to power outages. Several named areas, including Gatton, the Lockyer Valley, Mudgee, Singleton and South West Rocks, sit close to agricultural districts where the same storm system may affect commercial assets as well as homes and vehicles.

  • Photograph and video damage before moving items, especially where hail, wind or water has affected buildings, machinery or stored produce.
  • Keep damaged items where safe to do so, or keep samples and records if disposal is needed for health or biosecurity reasons.
  • Use the insurer’s published contact details or policy documents to verify anyone claiming to act on its behalf.
  • Check whether emergency work is genuinely temporary make-safe work or a larger repair contract that needs insurer approval first.

For primary producers, this is also a reminder that farm property insurance is usually split across different assets and limits. A house, machinery shed, fencing, livestock yards, irrigation equipment and stored hay may not all sit under the same section or excess. Flood, storm, accidental damage, spoilage and business interruption can also be treated differently, so the wording and schedule matter when assessing what has happened after a storm.

The practical lesson is to slow down any decision that creates a binding repair obligation unless safety demands immediate action. Farmers can still prioritise animal welfare, hazard removal and weatherproofing, but the claims process is easier to support when evidence, receipts, contractor details and insurer instructions are kept together from the start. In a widespread event, that organisation may be just as important as the first phone call.

Published:Wednesday, 18th Nov 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Insurance News

Storm Damage Brings a Fresh Claims Warning for Farmers
18 Nov 2026: Paige Estritori
A fresh Insurance Council of Australia warning about disaster chasers after the Queensland and New South Wales storms is highly relevant for farm businesses now moving from clean-up to claims. On 18 November 2026, the council said more than 9,000 claims had been lodged after severe weather across the two states from 11-17 November, with some operators allegedly approaching damaged properties and pushing repair work before insurers have approved it. - read more
Farm Package Revamp Signals a More Digital Insurance Market
11 Nov 2026: Paige Estritori
Prevail’s latest farm insurance update is a useful signpost for Australian primary producers watching how the rural insurance market is changing. Insurance News reported on 5 November 2026 that the Steadfast-owned underwriting agency has refreshed its farm package, now branded Prevail Elite Farm Insurance, with a clearer structure, higher stated capacity across some farm assets and new attention on technology-related exposures. - read more
New Dust Limits Put Farm Safety Records in the Insurance Spotlight
04 Nov 2026: Paige Estritori
New workplace exposure limits for airborne contaminants are moving from a regulatory issue to a practical farm risk-management concern, particularly for grain growers heading through harvest. With the national transition scheduled for 1 December 2026, recent state decisions to delay or stage some limits have created a patchwork of obligations that farm businesses should watch closely. - read more
Farm Flood Dispute Shows the Cost of Delayed Claims Handling
28 Oct 2026: Paige Estritori
A recent Australian Financial Complaints Authority determination involving a flooded farmhouse has put claims handling back under the microscope for rural policyholders, after the insurer was ordered to pay almost $432,000 across building repairs, additional temporary accommodation, professional costs and compensation for non-financial loss. The decision, dated 27 August 2026 and reported by Insurance News on 15 October 2026, is a useful reminder that the practical aftermath of a farm flood can extend well beyond the first clean-up. - read more
What Cyclone Alfred Recovery Teaches Farmers About Insurance
16 Sep 2026: Paige Estritori
Recent industry attention on insurance claims linked to ex-Tropical Cyclone Alfred is a timely reminder that severe weather losses rarely stop at damaged buildings. For farms across storm and flood-exposed regions, the real cost of an event can include cut access roads, damaged fencing, spoiled fodder, machinery downtime, livestock movement issues and weeks of operational disruption. - read more
Seasonal Bushfire Risk Puts Farm Cover Back in the Spotlight
09 Sep 2026: Paige Estritori
Australia’s latest seasonal bushfire outlook is a practical reminder that fire risk is not confined to the height of summer. For many farms, the exposure begins well before a catastrophic fire day is declared, as grass growth, drying winds, stored fodder, machinery movement and access limitations combine to create a more complex risk profile than a standard rural home policy can address. - read more


Farm Insurance Articles

What Does Farm Insurance Cover in Australia?
Farm insurance in Australia is usually built from several cover sections rather than one standard policy. This guide explains common inclusions, optional covers, limits and exclusions to check before comparing policies. - read more
Preparing for the Worst: Developing a Comprehensive Disaster Response Plan for Your Farm
As a farmer, you know that unexpected events can have a significant impact on your farm and your livelihood. Natural disasters, such as floods, fires, droughts, and storms, can occur at any time and have devastating consequences. That's why it's crucial to have a comprehensive disaster response plan in place to protect your property, assets, and, most importantly, your loved ones and livestock. - read more
Agribusiness Liability Risks Facing Australian Farmers
Australian farming businesses face liability risks that go well beyond crop production and livestock management. From visitor injuries and unsafe produce to chemical use, worker safety, machinery incidents and emerging technology risks, understanding where liability can arise is an important part of protecting a farm's long-term resilience. - read more
10 Ways Australian Farmers Can Manage Farm Insurance Costs Without Reducing Essential Cover
Farm insurance is an important part of managing agricultural risk, but premiums still need to fit the realities of farm cash flow. This guide explains practical ways Australian farmers can review cover, reduce avoidable costs and keep insurance aligned with the risks, assets and operations on their farm. - read more
Income Protection Insurance for Hobby Farmers: What to Consider
Hobby farming may not be your main source of income, but it can still be financially important. If illness or injury prevents you from working, income protection insurance may help replace part of your income while you recover, depending on the policy terms. - read more
Farm Succession Planning for Rural Australian Families
Farm succession is the planned transfer of farm ownership, management and knowledge from one generation to the next. For rural Australian families, it can involve complex family, legal, financial and operational decisions, so starting early and using a structured process can help reduce uncertainty. - read more

Need a Quote?
Start your free farm insurance quote comparison here.

Start Here ...

Farm Type:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.

Need a
FARM INSURANCE
QUOTE?

Knowledgebase
Insurance Deductible:
the amount that an insured is required to contribute toward an insurance claim as stipulated in an insurance policy. Otherwise known as the "policy excess".